Introduction
Finding affordable health insurance can feel confusing, especially when you are comparing plans, premiums, deductibles, and government assistance. The Obamacare Health Insurance Marketplace, officially known as the Health Insurance Marketplace, was created to help eligible individuals and families compare and purchase health insurance plans in one place.
Health insurance is an important part of protecting yourself and your family from unexpected medical expenses. A routine doctor’s visit, emergency treatment, prescription medicine, or hospital stay can become very expensive without insurance coverage. For this reason, many people look for affordable options that provide access to essential healthcare services.
The Obamacare Health Insurance Marketplace was created to make the process of finding health coverage easier. Through the Marketplace, eligible consumers can compare different health insurance plans, understand what each plan covers, and determine whether they qualify for financial assistance that can reduce the cost of monthly premiums or other healthcare expenses.
“Obamacare” is a commonly used name for the Affordable Care Act (ACA). The ACA introduced major changes to the American health insurance system and established the Health Insurance Marketplace as a place where individuals and families can shop for qualifying health plans.
This guide explains what the Obamacare Health Insurance Marketplace is, how it works, who may qualify, what types of plans are available, and what consumers should consider before choosing coverage.
What Is the Obamacare Health Insurance Marketplace?
The Health Insurance Marketplace is a service where people can shop for health insurance plans that meet standards established under the Affordable Care Act. It is designed primarily for individuals and families who do not have access to suitable health coverage through an employer, Medicare, Medicaid, or another qualifying program.
The Marketplace allows consumers to compare plans based on important factors such as:
- Monthly premium costs
- Deductibles
- Copayments and coinsurance
- Provider networks
- Prescription drug coverage
- Covered healthcare services
- Estimated financial assistance
Instead of contacting multiple insurance companies separately, consumers can review available Marketplace options in one place.
The exact plans and prices available can vary depending on factors such as where a person lives, household size, income, age, and the number of people applying for coverage. This means that one person’s best plan may not be the best option for another family.
How Does Obamacare Health Insurance Work?
When a person applies for Marketplace coverage, they generally provide information about their household, income, and other relevant circumstances. Based on that information, the application may determine whether they are eligible for Marketplace coverage or whether another program may be more appropriate.
Some applicants may qualify for financial assistance. Depending on eligibility, this assistance can help lower the amount paid for health insurance.
After reviewing the available options, the consumer chooses a plan and pays the required premium to maintain coverage.
Once enrolled, the insurance plan helps pay for covered medical services according to the plan’s rules. The consumer may still need to pay some healthcare costs, including deductibles, copayments, or coinsurance.
Understanding these terms is important:
Premium
A premium is the amount paid regularly to maintain health insurance coverage. Many people pay their premium every month.
Deductible
A deductible is generally the amount a consumer pays for certain covered healthcare services before the insurance plan begins paying its share according to the policy rules.
Copayment
A copayment, often called a copay, is a fixed amount a person may pay for a covered service, such as a doctor visit or prescription.
Coinsurance
Coinsurance is usually a percentage of the cost of a covered service that the consumer pays after meeting applicable plan requirements.
Out-of-Pocket Maximum
Marketplace plans also have limits on certain covered medical expenses that an enrollee may have to pay during a plan year. The details depend on the specific plan and applicable rules.
What Does an Obamacare Marketplace Plan Cover?
Marketplace health plans are required to provide coverage for a range of important healthcare services. These services are often referred to as essential health benefits.
Although coverage details can vary by plan, Marketplace coverage generally includes categories of care such as:
- Outpatient and doctor services
- Emergency services
- Hospital care
- Pregnancy and maternity care
- Mental health and substance use treatment
- Prescription drugs
- Rehabilitative services
- Laboratory services
- Preventive and wellness services
- Pediatric services
Preventive care can be particularly valuable because it focuses on helping people identify health concerns early. Depending on the service and the plan’s rules, preventive healthcare may include screenings, vaccinations, and wellness services.
Consumers should always review the details of a specific plan before enrolling. A service being included as a general benefit category does not mean every provider, treatment, medication, or situation is covered in exactly the same way.
The Different Marketplace Plan Categories

Marketplace plans are commonly organized into metal categories: Bronze, Silver, Gold, and Platinum. These categories are designed to provide a general indication of how healthcare costs may be shared between the insurance company and the consumer.
Bronze Plans
Bronze plans often have lower monthly premiums but higher costs when medical care is needed. They may appeal to people who want protection from major medical expenses and do not expect frequent healthcare use.
Silver Plans
Silver plans generally offer a balance between monthly premium costs and out-of-pocket expenses. For some eligible consumers, additional savings may be connected to selecting a Silver plan.
Gold Plans
Gold plans may have higher monthly premiums but lower costs when receiving covered medical care compared with plans that place more costs on the consumer.
Platinum Plans
Platinum plans generally have higher premiums and lower cost-sharing when covered medical services are used.
The right category depends on an individual’s budget, expected healthcare needs, prescription requirements, and financial situation. Choosing the plan with the lowest monthly premium is not always the cheapest option overall.
For example, a person who frequently visits specialists or takes expensive medications may save money with a plan that has a higher premium but lower costs when care is received.
Who Can Apply for Marketplace Coverage?
Eligibility for Marketplace coverage depends on individual circumstances and applicable program requirements. In general, applicants must meet certain residency and legal-status requirements.
People commonly explore Marketplace coverage when they:
- Are self-employed
- Work for an employer that does not provide health insurance
- Are unemployed
- Are between jobs
- Are not eligible for other qualifying coverage
- Need coverage for themselves or their family
An application can also help determine whether a person may qualify for programs such as Medicaid or the Children’s Health Insurance Program, depending on eligibility rules.
Financial Assistance and Premium Savings

One of the most important features of the Obamacare Health Insurance Marketplace is the possibility of financial assistance for eligible applicants.
Some consumers may qualify for premium tax credits, which can reduce the cost of monthly insurance premiums. Eligibility is based on factors such as household income and family size, along with other applicable requirements.
Some eligible Marketplace consumers may also qualify for additional savings that reduce certain out-of-pocket costs.
Because financial assistance can significantly change the actual cost of insurance, it is often helpful to complete an application and review the available results rather than assuming that a plan is unaffordable based only on its listed premium.
It is also important to provide accurate and updated information. Changes in income, household size, marriage, divorce, or other circumstances may affect eligibility and financial assistance.
When Can You Enroll?
Marketplace coverage is generally available during an annual Open Enrollment Period. During this time, eligible consumers can apply for a new plan, compare options, or make changes to existing Marketplace coverage.
Outside the regular enrollment period, certain life events may allow a person to qualify for a Special Enrollment Period. Examples can include changes such as losing qualifying health coverage, getting married, having a baby, or moving under qualifying circumstances.
Enrollment rules and deadlines can change, so consumers should check the official Marketplace information for the current dates and requirements before making decisions.
How to Choose the Right Obamacare Health Insurance Plan
Selecting a health insurance plan requires more than simply choosing the lowest premium. A good plan should fit both your budget and your healthcare needs.
Here are several important factors to consider.
1. Estimate Your Healthcare Needs
Think about how often you visit doctors, whether you need specialist care, and whether you take regular prescription medications. Someone who rarely needs medical services may choose differently from someone who receives ongoing treatment.
2. Check the Provider Network
If you already have a preferred doctor or hospital, check whether they participate in the plan’s network. Going outside a plan’s network can result in higher costs or reduced coverage depending on the policy.
3. Review Prescription Drug Coverage
People who take regular medications should check the plan’s drug list, also called a formulary. A medication may be covered differently by different plans.
4. Compare Total Potential Costs
Do not compare premiums alone. Consider the deductible, copayments, coinsurance, and potential costs for services you expect to use.
5. Understand the Plan Documents
Insurance companies provide documents explaining benefits, coverage limitations, and cost-sharing. Reading these documents can help prevent unexpected expenses later.
Benefits of Using the Health Insurance Marketplace
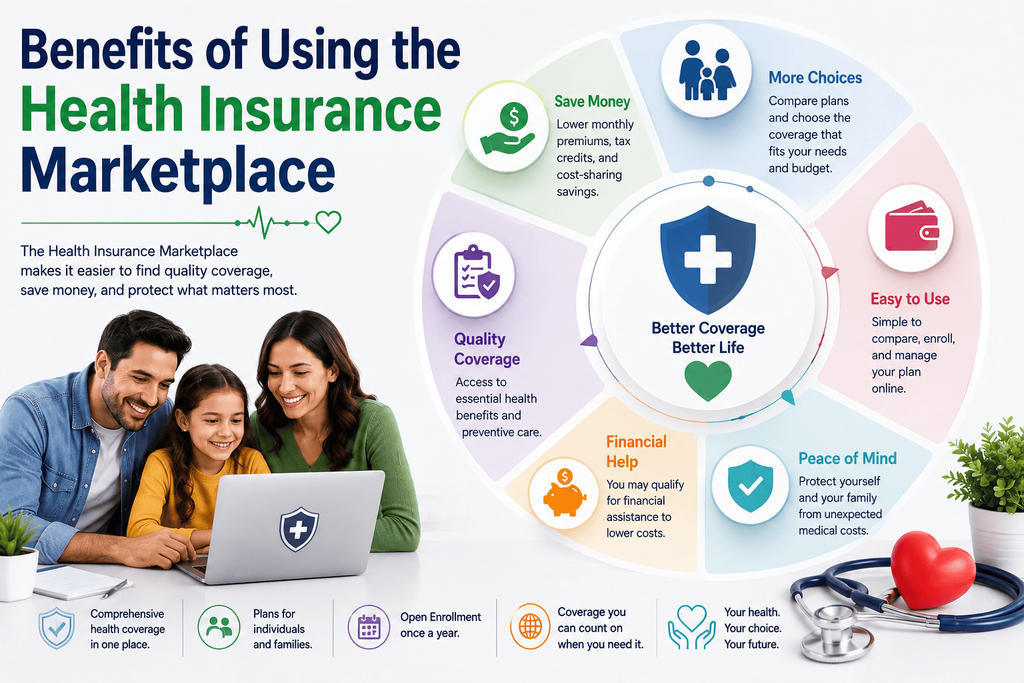
The Marketplace offers several advantages for consumers searching for individual or family health coverage.
First, it provides a structured way to compare multiple plans. Instead of reviewing insurance options without a clear comparison, consumers can evaluate premiums, deductibles, benefits, and other important features.
Second, eligible applicants may receive financial assistance that makes health insurance more affordable.
Third, Marketplace plans provide coverage for important categories of healthcare services established under the Affordable Care Act.
Finally, the Marketplace application can help direct eligible individuals toward other coverage programs when appropriate.
Common Mistakes to Avoid
When shopping for Obamacare health insurance, consumers should avoid rushing into a decision.
One common mistake is choosing a plan based only on the monthly premium. A very low premium may come with a high deductible or significant costs when healthcare services are needed.
Another mistake is failing to check the provider network. Before enrolling, verify whether your preferred doctors, hospitals, and specialists participate in the plan.
It is also important to report changes in household or income information when required. Outdated information may affect eligibility or financial assistance.
Finally, do not wait until the last minute to explore enrollment options. Reviewing plans early gives you more time to compare benefits and understand your choices.
What is the Health Insurance Marketplace (Obamacare)?
The Marketplace (HealthCare.gov or state-based equivalents) is a service created under the Affordable Care Act (ACA) where individuals, families, and self-employed workers can shop for, compare, and buy ACA-compliant health insurance plans.
When can I sign up for coverage?
You can enroll during the annual Open Enrollment Period (OEP), which typically runs from November 1 to January 15 in most states. To have coverage start on January 1, you generally must select a plan by December 15. Outside of OEP, you can only sign up if you qualify for a Special Enrollment Period (SEP) triggered by a qualifying life event (e.g., losing employer coverage, getting married, having a baby).
What do the metallic plan tiers (Bronze, Silver, Gold, Platinum) mean?
The tiers reflect how you and the plan split healthcare costs, not the quality of care:
- Bronze: Lowest monthly premiums, highest out-of-pocket costs/deductibles.
- Silver: Moderate premiums and deductibles; eligible for Cost-Sharing Reductions (CSRs) if your income qualifies.
- Gold: Higher monthly premiums, lower out-of-pocket costs.
- Platinum: Highest monthly premiums, lowest out-of-pocket costs.
How do subsidies (Premium Tax Credits) work?
Subsidies reduce your monthly premium based on your estimated annual household income and family size. When you apply, the Marketplace estimates your subsidy and pays it directly to the insurer. At tax time, your actual income is reconciled with your application estimate.
Can I be denied coverage or charged more for pre-existing conditions?
No. Under ACA rules, Marketplace plans cannot deny coverage, drop you, or charge higher premiums due to pre-existing conditions like diabetes, asthma, or cancer.
What essential benefits must every Marketplace plan cover?
All Marketplace plans must cover 10 essential health benefit categories, including emergency services, hospitalization, maternity/newborn care, mental health services, prescription drugs, lab services, pediatric care, and free preventive care (e.g., vaccines and annual checkups).
What is the difference between an HMO, EPO, and PPO plan?
- HMO: Requires selecting a Primary Care Physician (PCP) and getting referrals for specialists. Care outside the network is generally not covered.
- EPO: Doesn’t require referrals for specialists, but out-of-network care is not covered except in emergencies.
- PPO: Offers the most flexibility to see specialists without referrals and provides some coverage for out-of-network providers, usually at a higher cost.
What happens if I underestimate or overestimate my income on the application?
If your actual income ends up higher than estimated, you may have to repay part or all of the excess tax credits when filing your taxes. If your income drops mid-year, updating your Marketplace account immediately adjusts your subsidy upwards to avoid overpaying premiums.
Conclusion
The Obamacare Health Insurance Marketplace can be an important resource for individuals and families looking for affordable health insurance coverage. It provides a central place to compare qualifying plans, review healthcare benefits, and determine whether financial assistance may be available.
The best health insurance plan is not necessarily the one with the lowest monthly premium. A strong choice should balance premium costs with deductibles, provider access, prescription coverage, and expected healthcare needs.
Before enrolling, take time to compare your options carefully and review the official information for current eligibility rules, enrollment dates, available plans, and financial assistance. By understanding how the Marketplace works, consumers can make more informed decisions and choose health coverage that better fits their budget and healthcare needs.
For anyone exploring individual or family health insurance, the Obamacare Health Insurance Marketplace can be a useful starting point for understanding available coverage options and finding a plan that offers valuable protection against the cost of medical care.